We're building the future of agentic promotions. Sign up for early access!
Sign up
We're building the future of agentic promotions. Sign up for early access!
Sign up 
Gift cards are convenient for shoppers, but they’re also a popular payment method for scammers. Consumers reported $15.9 billion in total fraud losses to the Federal Trade Commission in 2025, up from more than $12 billion in 2024. According to FTC data cited by AARP, Gift card scams alone accounted for at least $212 million in reported losses in 2024.
These scams work because the scammer doesn’t need your bank account. They need the card number and PIN, and once those are shared, the balance can be gone before the victim notices.
For shoppers, the biggest warning sign is simple: a stranger tells you to buy a gift card and share the numbers. For retailers, the problem is broader. Fraud can happen before a card reaches the customer, at the point of sale, or through employee access.
Gift card scams are schemes that trick someone into giving a scammer access to the value stored on a gift card. The scam can happen through a phone call, email, text message, social media account, fake website, or physical tampering with a card.
Most gift card scams fall into three broad groups. Payment scams convince a victim to purchase a legitimate gift card and hand over the number and PIN. Theft scams steal the value from a card through tampering, hacking, fake balance sites, or other methods. Insider abuse happens when someone with legitimate access to a retailer’s gift card system misuses that access.
The story changes, but the objective is usually the same: obtain gift card value and convert it into money, merchandise, or another form of value.
Scammers like gift cards because they behave much like cash once the redemption information has been handed over. A scammer can convince someone to purchase a card, obtain its number and PIN, and use that information without ever taking physical possession of the card.
The FTC says scammers commonly create urgency, tell victims which gift card to purchase, direct them to particular stores, and then ask for the card number and PIN. In some cases, they remain on the phone while the victim travels to a store and loads the card.
The code can then be sold or used to purchase merchandise. HSI says gift card fraud networks have used stolen redemption information to purchase consumer goods that are shipped overseas and resold. In a July 2026 federal case, prosecutors alleged that gift cards obtained through romance fraud, elder fraud, hacking, theft, and other scams were used to purchase high-value electronics. Those electronics were then shipped to China and Hong Kong.
That means the transaction doesn’t necessarily end when the victim gives away the code. The gift card can become part of a larger chain involving resellers, merchandise, and organized fraud networks.
The following six categories cover the major gift card scam patterns consumers and retailers should understand.
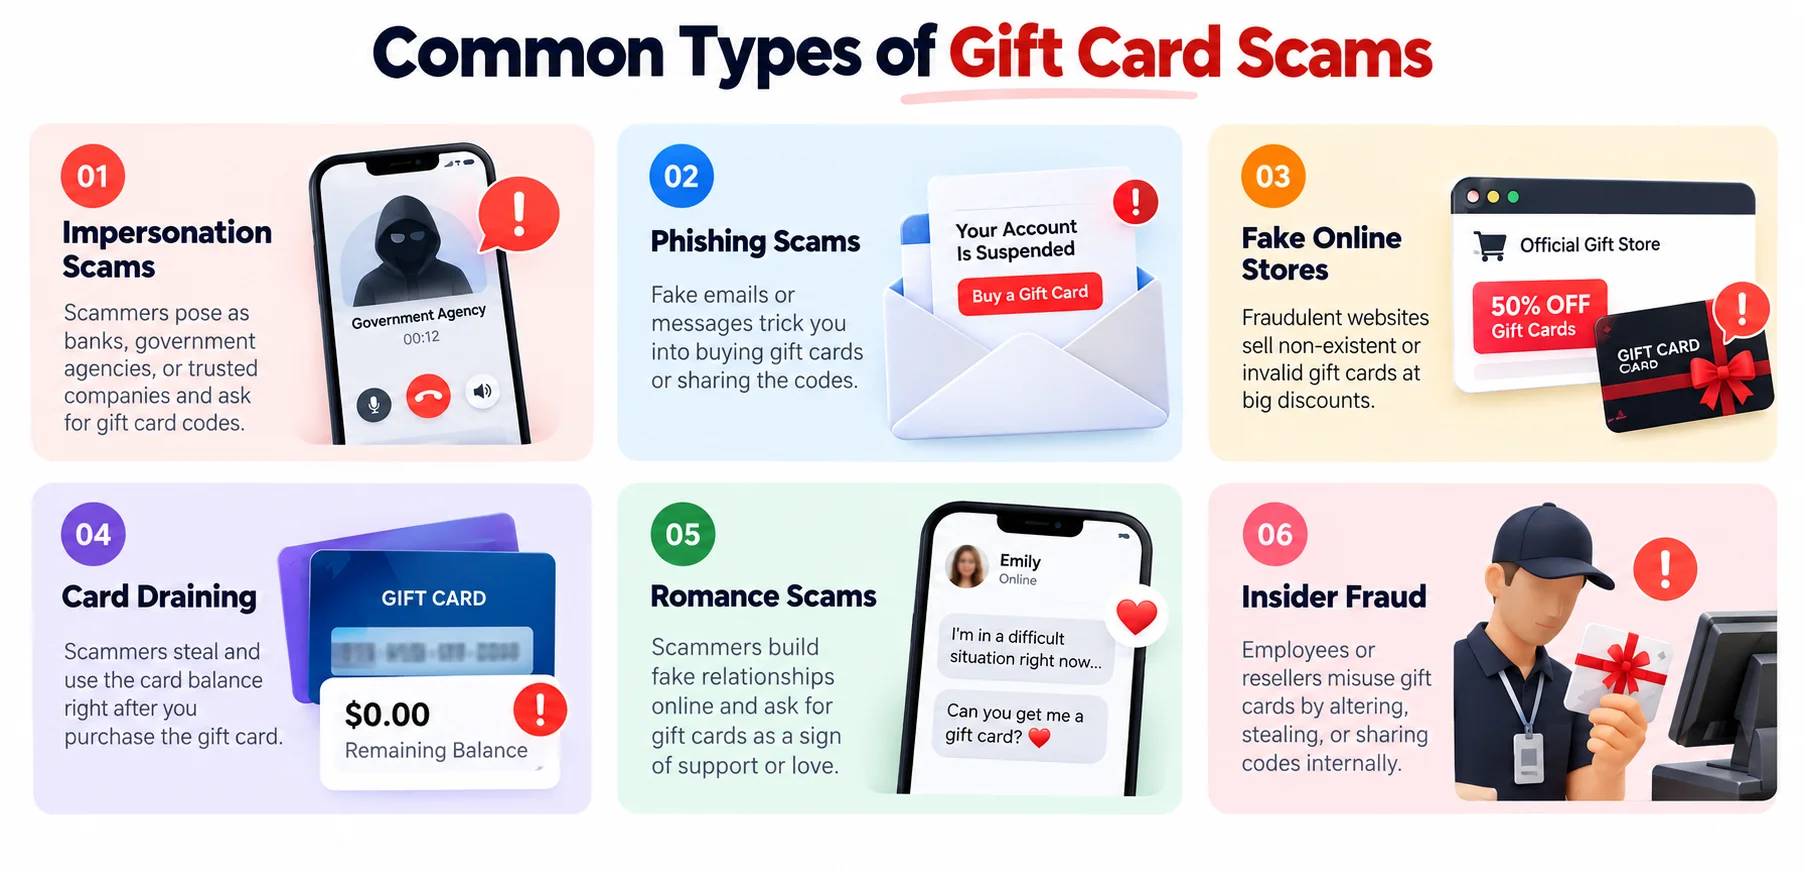
In this scam, someone pretends to represent the IRS, Social Security Administration, police, or another government agency. The victim is told that they owe money, face arrest, or need to pay a fine immediately. The scammer then instructs them to purchase gift cards and provide the numbers and PINs.
The IRS doesn’t demand payment through gift cards. The FTC similarly warns that government agencies won’t demand immediate payment by gift card.
A federal case shows how quickly this can turn into a real loss. According to the U.S. Department of Justice, a caller pretending to be an IRS representative contacted a South Carolina woman. The caller said she owed taxes and would be arrested if she didn’t pay. She purchased a $2,000 Target gift card and gave the caller the card number and access code. Transaction records and store video later showed that the card was redeemed less than an hour later, at a Target store in Maryland, to purchase Apple products.
The red flag is any demand to pay a government debt, fine, or tax bill with a gift card. Hang up and contact the agency through an official website or phone number.
These scams use a trusted brand to make the payment request look legitimate. The scammer may claim to be from a technology company, internet provider, phone company, or another business and say there’s a problem with the victim’s account or service.
A common version involves a fake security warning or unexpected call claiming that a computer has a virus. The victim is told that a technician can fix the problem, but payment must be made with a gift card.
The FTC has repeatedly warned about this pattern. In 2025, the agency reported robocalls in which scammers impersonated companies such as AT&T, Spectrum, and Comcast Xfinity. The callers offered supposed discounts of 40% to 50% if customers paid upfront with gift cards. The scammers could also ask for account information under the pretext of applying the discount.
The FTC has also specifically warned that legitimate tech support companies don’t require customers to pay for technical support with gift cards.
Treat any gift card payment request that comes from an unexpected call, pop-up, email, or message as a scam. Instead of using the contact information provided by the caller, visit the company’s official website and contact it directly.
A boss gift card scam is a form of impersonation and business email compromise. The scammer pretends to be an executive, manager, or colleague and asks an employee to buy gift cards for an event, client, employee reward, or urgent business request.
The message is often short and urgent. The scammer may ask the employee to buy several cards and send photos or the numbers and PINs from the back. They may promise reimbursement later.
The FTC continues to warn about this scam. In January 2026, it described a common scenario in which someone impersonates a boss, asks for an urgent favor, and instructs an employee to purchase gift cards and send the numbers. The FTC recommends verifying the request using a phone number or email address already known to be genuine.
The FTC has also documented cases where scammers target new employees after seeing hiring announcements on social media. The fake boss then asks the new employee to purchase gift cards and send the numbers.
Watch for secrecy and urgency. A legitimate executive shouldn’t require an employee to bypass normal purchasing controls simply because the request is urgent.
These scams exploit trust and emotion rather than authority. A scammer may pretend to be a family member who has been arrested, injured, stranded, or otherwise needs immediate help. Another version involves an online romantic partner who suddenly needs money for travel, medical treatment, a legal problem, or another emergency.
Voice cloning can make family emergency scams harder to recognize. The FTC warns that scammers may use cloned voices to sound like a victim’s loved one. Romance scammers may also build a relationship over time before asking for gift cards or other payments.
The FTC has described romance scammers posing as military personnel, doctors, diplomats, and other professionals. After developing an online relationship, they may ask for gift cards, presents, or money because of a supposed emergency.
The red flag is emotional pressure combined with a request for immediate payment. If someone claims to be a relative, call that person directly using a number you already have. For an online relationship, never send gift cards to someone you haven’t met in person.
Not every gift card scam begins with a threat. Some begin with an opportunity that looks too good to ignore.
A scammer may tell someone they have won a sweepstakes or gift card but must pay a processing fee, tax, or shipping charge first. In an overpayment scam, the victim receives a fake check for more than expected and is told to return the difference by buying gift cards.
The FTC says real prizes are free and legitimate sweepstakes don’t require winners to pay fees to receive their prizes.
Another version targets bargain shoppers. A stranger may offer a gift card far below face value through an online marketplace, auction site, or social media listing. The card may be stolen, already drained, or otherwise unusable.
The same principle applies to websites that imitate legitimate gift card or balance-check pages. A shopper who enters a card number and PIN into an unofficial site may be giving those details directly to a scammer.
The warning signs here are an unusually cheap card, an unexpected prize, or a request to pay a fee before receiving something you supposedly won.
Some gift card fraud happens without anyone tricking the shopper into voluntarily giving away a code.
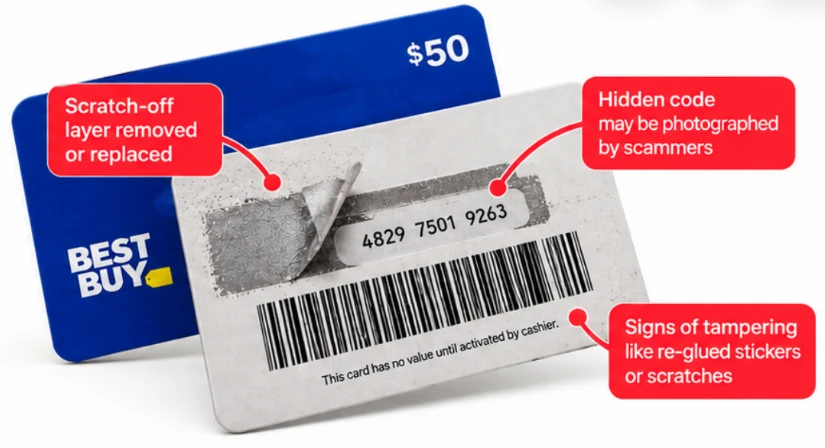
In gift card draining schemes, criminals obtain card numbers and PINs before the legitimate customer uses the card. They may remove protective stickers, record the information, reseal the packaging, and return the card to the store shelf. When a shopper later purchases and activates the card, the criminal monitors the balance and drains it.
HSI’s Project Red Hook describes this type of organized activity. It explains that criminals can tamper with cards, replace them on retail displays, and drain the value after a legitimate customer loads money onto them. HSI also identifies online attacks and victim-assisted fraud as additional methods.
The FTC warned consumers in December 2024 that scammers can remove protective stickers or scratch gift cards to obtain the card number and PIN before replacing the cards on store displays.
There’s another risk on the merchant side: employee or insider gift card fraud.
A September 2026 TwistedSifter article republished an older Reddit account from a former loss prevention worker. According to the account, a part-time employee at a clothing retailer repeatedly bought about $2,000 in gift cards from each of four stores. She used an employee discount of roughly 30%. The account says the employee purchased more than $90,000 in gift cards over seven months. The post also says corporate chose not to intervene. TwistedSifter presented this as a republished personal account, not as a newly reported 2026 incident. The story also doesn’t establish that the cards were actually resold.
For a retailer, the lesson isn’t simply that an employee bought a lot of gift cards. It’s that gift card purchasing needs the same controls as other high-risk transactions. Employee discounts can be excluded from gift card SKUs, individual purchase limits can be established, and unusual purchases can be monitored across locations.
| Scam type | Who it targets | Red flag | How shoppers avoid it | How merchants can help prevent it |
|---|---|---|---|---|
| Government or IRS impersonation | Consumers | Threat of arrest or immediate payment | Contact the agency directly | Train cashiers to question urgent, unusual purchases |
| Fake company or tech support | Consumers | Account or computer problem requiring gift card payment | Use the company's official website | Display clear warnings that gift cards aren't accepted as payment |
| Boss or CEO request | Employees | Urgent and secret executive request | Verify through a known contact method | Require approval for gift card purchases |
| Family emergency or romance | Consumers | Emotional pressure and secrecy | Contact the person directly | Train staff to recognize customers under pressure |
| Prize, overpayment, or discounted card | Consumers | Fee, fake check, or unrealistic discount | Don't pay to receive a prize or buy from unknown sellers | Educate customers and provide official balance-check information |
| Draining, tampering, and insider fraud | Shoppers and retailers | Damaged packaging or unusual employee purchases | Inspect cards and keep receipts | Tamper controls, purchase limits, monitoring, and access controls |
Most gift card scams have several warning signs in common.
The FTC’s core rule is straightforward: no legitimate business or government agency will tell you to buy a gift card to pay them.
Speed matters. Once the scammer has the card number and PIN, the balance can disappear quickly.
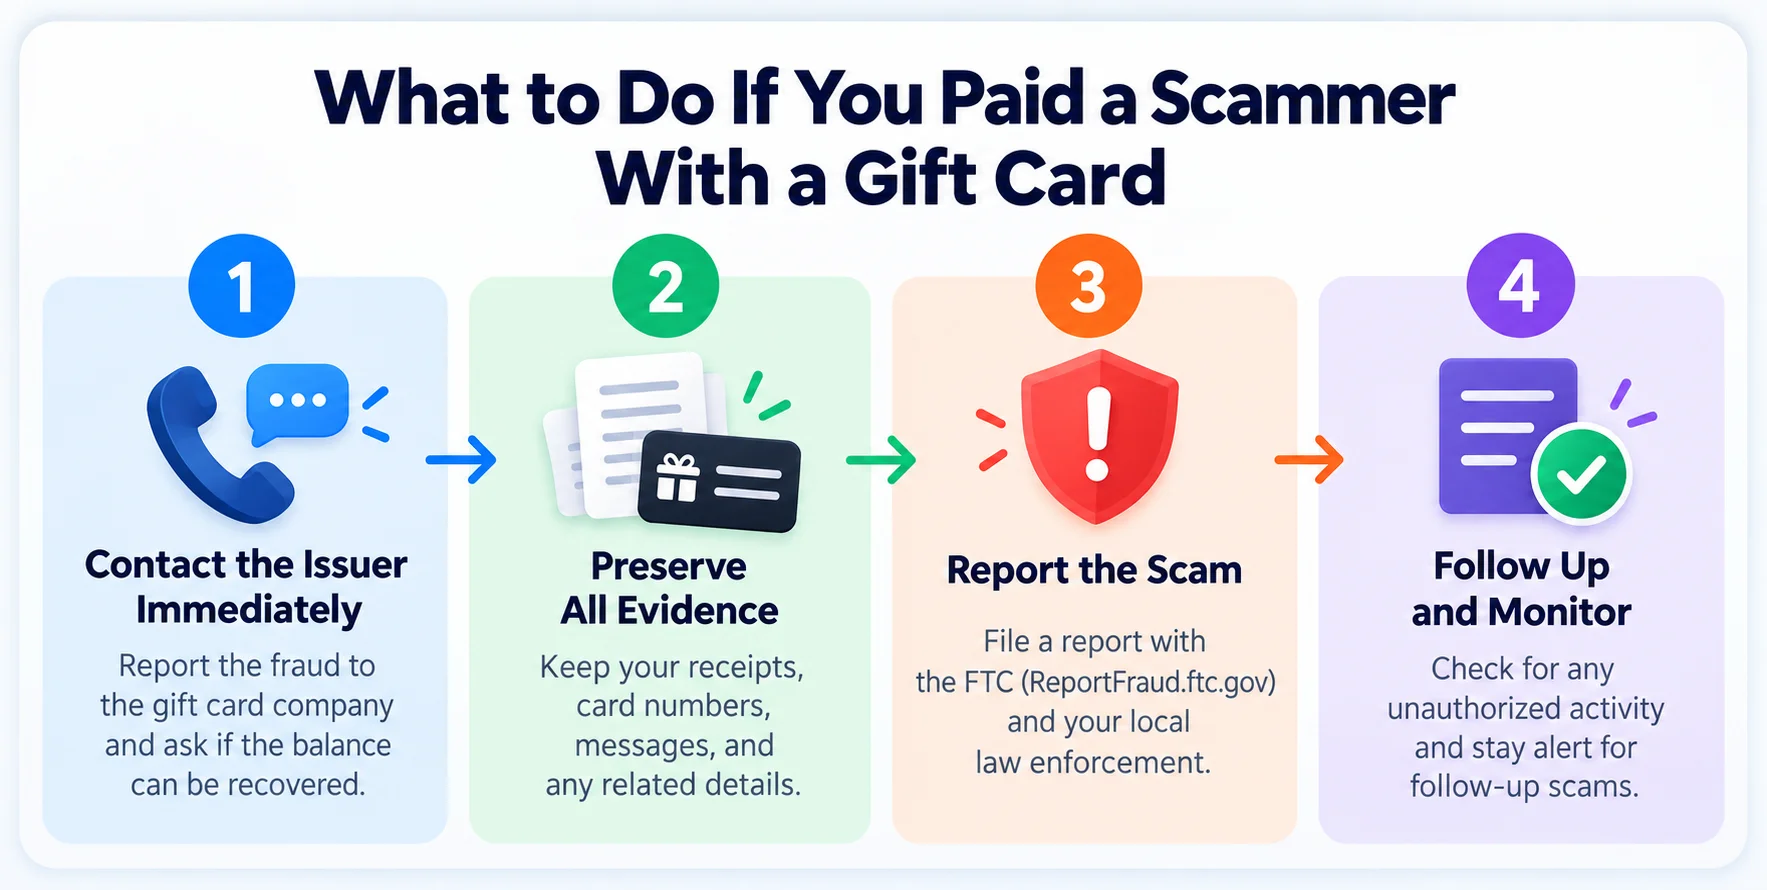
Don’t wait because you think the amount is too small. Reporting quickly gives the gift card issuer more information to work with while the funds may still be available.
Gift card fraud can create costs for a retailer even when the retailer wasn’t the scammer’s intended victim.
When a customer’s card is drained before they use it, the customer generally contacts the retailer first. That creates support costs, refund requests, investigation work, and potential damage to the customer’s trust in the brand.
Retailers can also face operational losses from tampering, fraudulent activations, employee abuse, stolen codes, and chargebacks associated with fraudulent purchases.
There’s also a broader risk. HSI says organized gift card fraud networks can use stolen gift card value to purchase merchandise that is later shipped overseas and resold.
For merchants, gift card security is therefore not just a customer-service issue. It’s a combination of fraud prevention, loss prevention, operational controls, and brand protection.
Retailers can reduce gift card fraud by combining physical controls, digital monitoring, employee procedures, and a clear response process.
Keep high-value gift cards behind the counter or in controlled displays where appropriate. Tamper-evident packaging makes it harder for criminals to access card numbers and PINs without leaving visible signs.
Train cashiers to check packaging before activation. If a card appears scratched, resealed, wrinkled, or altered, the employee should remove it from sale and report it.
Activation should happen at the register as the final step. Where possible, keep sensitive PIN information protected until activation.
Use long, unpredictable gift card codes and separate PINs rather than easily guessed sequences.
Rate-limit online balance checks and monitor repeated lookups from the same device or source. A sudden burst of balance checks can be a useful fraud signal.
Set velocity rules for unusual gift card purchasing patterns. For example, multiple high-value purchases in a short period should receive additional scrutiny.
For large first-time business orders, merchants can consider delaying activation until payment has cleared and monitoring redemption activity after activation.
Employees are often the final point of contact before a gift card transaction becomes irreversible.
Train cashiers to ask a simple question when a customer is buying a large amount of gift cards under pressure: “Is someone asking you to pay them with these?”
Scammers sometimes coach victims to avoid store employees. A trained cashier can therefore become an important fraud-prevention control.
Employee purchases should also be monitored. Consider excluding gift card SKUs from employee discounts, setting per-employee purchase limits, reviewing high-value activations, and monitoring purchases across multiple locations.
Access permissions should also be separated where possible. The employee who can activate a card shouldn’t automatically have unrestricted permission to void, refund, or adjust the same transaction.
When retailers identify organized gift card draining or tampering, preserve transaction records, card information, receipts, video footage, and other relevant evidence.
HSI’s Project Red Hook specifically addresses organized gift card fraud and encourages cooperation between retailers and law enforcement.
Gift card fraud prevention works best when merchants can manage gift card transactions and identify suspicious activity from the same system. 99minds combines gift card management with fraud prevention through its nSure integration, helping merchants add another layer of protection to gift card transactions.
Here are some ways 99minds supports gift card fraud prevention:
99minds integrates with nSure to add a fraud prevention layer to gift card transactions. This helps merchants identify potentially risky transactions as part of their gift card management workflow.
Merchants can manage gift card issuance, activation, and redemption through a centralized system, making it easier to maintain control over the gift card lifecycle.
Tracking gift card transactions and redemption activity gives merchants greater visibility into how gift cards are being used and can help them investigate unusual activity.
Gift card management controls can be combined with fraud prevention processes to reduce the risk of suspicious transactions becoming a larger loss.
By bringing gift card management and fraud prevention into a connected workflow, merchants can manage gift card activity more consistently across their operations.
For merchants, the goal isn’t to rely on a single fraud control. Combining fraud screening with secure gift card management and transaction visibility can create a more structured approach to preventing gift card fraud.
For consumers, the most important rule is simple: gift cards are for gifts, not for paying strangers, government agencies, technical support representatives, or supposed business emergencies.
If you’ve already given a scammer a gift card number, contact the issuer immediately and keep your card and receipt. Speed matters because the balance may still be recoverable.
For retailers, preventing gift card fraud requires more than warning customers. Physical card security, controlled activation, employee policies, transaction monitoring, and a clear incident-response process all play a role.
The strongest gift card programs treat fraud prevention as part of the entire customer journey, not as a problem that starts only after money has been stolen.
If you sell gift cards, 99minds gives you one place to issue, activate, redeem, and track them across your online and physical stores, with fraud screening through its nSure integration. To see how it can fit your gift card program, you can book a demo with the 99minds team.